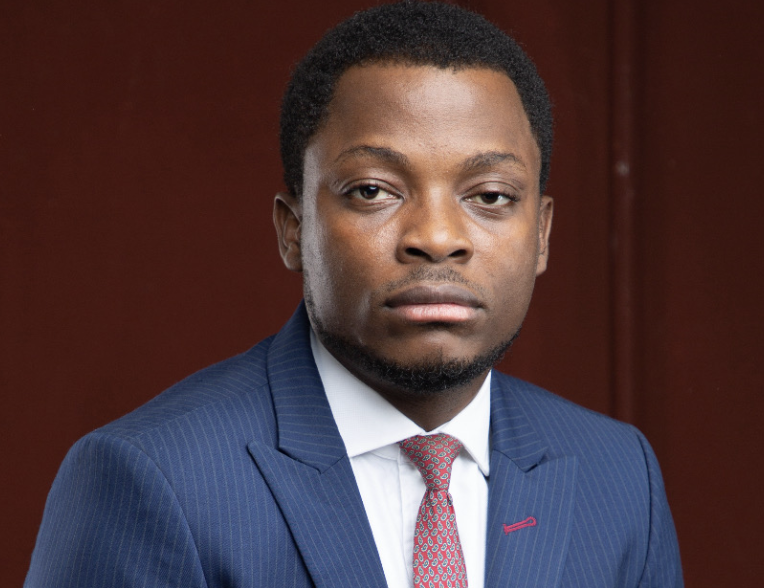
By Emmanuel Okogba
Africa’s fintech sector has produced some of the continent’s most visible startups, yet financial exclusion, whilst reducing, remains stubbornly high. For Abolore Salami, a Nigerian entrepreneur and fintech founder, this paradox points to a deeper problem: too many financial products are built for how founders wish Africans managed money, rather than how they actually do.
Salami is the founder of Riby, a digital financial services platform focused on cooperatives, credit unions, and group-based finance systems that have quietly supported savings, credit, and investments across African communities and families for decades. His work challenges the assumption that financial inclusion begins with individual banking apps.
“Before fintech arrived, people were already saving, lending, and investing together,” Salami says. “The problem wasn’t behaviour. It was infrastructure.”
That insight shaped Riby’s approach. Instead of attempting to replace cooperatives, the company set out to digitise them by bringing transparency, governance, and scale to systems that already enjoyed deep trust at the grassroots.
Through Riby’s Co-Banking platform, more than 750,000 cooperative membershave engaged digitally, with 350,000 directly onboarded, despite device-access limitations in many communities. Beyond its proprietary products, Riby has powered large-scale financial inclusion programmes, onboarding over four million Nigerians through the Bank of Industry’s GEEP initiatives, including MarketMoni, TraderMoni, and FarmerMoni.
Additional custom platforms co-designed by Riby Finance, such as PlaX and the Dynamo Platform have supported over seven million users across federal and state-backed programmes and development finance funds, including the World Bank-funded NG CARES (2021-2025), SEEP, KWASSIP (2020-2022), MSME Survival Fund, National Women Empowerment Fund NAWEF and the Nigerian Consumer Credit initiatives (2025).
For Salami, these numbers matter because they represent real participation in formal financial systems. “Inclusion isn’t about app downloads,” he explains. “It’s about whether people can reliably save, borrow, and grow economically over time. What he terms Economic Inclusion, the next level to financial inclusion.”
His thinking is shaped by a career that spans consulting, power technology, and venture building. Before founding Riby, Salami served as Vice President at Venture Garden Group’s PowerTech unit, where he led teams that generated over $10 million in revenue in under three years by securing national utility and grid-level clients. He was also the founding General Manager at VisaCover, one of Nigeria’s earliest digital insurance aggregation platforms, now Casava.com, which has gone on to raise over $4 million to expand digital access to reliable insurance services for businesses and families. He has advised and supported global banking, payment and wealth management fintechs that have processed over $3 billion dollars in transactions.
These experiences taught him that technology only succeeds when it fits the realities of its environment. “You can’t design financial products in isolation,” he says. “You have to understand regulation, infrastructure constraints, and human behaviour all at once.”
One of the most common mistakes Salami sees among fintech founders is underestimating these realities. Many, he argues, focus on growth metrics without building systems that can last. Others treat regulation as an obstacle rather than a design requirement.
“Financial services are not sprints. If you try to move fast without understanding regulation, you’re building on sand,” he says.
Salami’s approach emphasises durability over hype. Riby-supported systems have helped mobilise significant economic value, including approximately $200 millionunder GEEP programmes between 2017 and 2021, over $250 million under World Bank NG CARES (RA3) from 2021 to 2025, and the PlaX-powered custom system, which supports N40 billion in consumer credit delivered by CrediCorp in under two years (late 2024 to 2025).
For founders planning to build fintech products in Africa, Salami’s advice is direct: start with the problem, not the pitch. Spend time with users. Understand existing financial behaviour. Build for trust before scale. One proud example he gave of a FinTech that has done this is MoniePoint. They built deeply to create a truly inclusive market enabled by technology.
“Africa doesn’t need more flashy fintechs. It needs institutions, products that respect how people already organise money and help those systems grow responsibly,” he adds.
In closing, he emphasized the need to think about these four elements strongly when building your company:
• The People – Who will be involved in this business from co-founders to board members to investors, management and teams. A strong and efficient people placement and management process is key every step of the way. One wrong decision on people can kill the business early and you need to ensure the right controls are in place at all levels.
• The Market – Your market’s structural economics, business unit economics and product pricing must reflect the realities of your business and your market. For example, if your technology cost is too high compared to your expected revenue / revenue growth, say on a long-term cost-to-revenue per customer basis, then you don’t yet have a sustainable business model, and you need to visit the drawing board again.
• Timing and Problem-Solution Fit: Is this the right time for your business, are you too early or too late based on your offering? Are you building a solution looking for a problem to solve or is there really a market need and a problem your solution is the best available to solve. Don’t waste your time building something that is not needed at said time. In the near future, building without AI will be a waste of time.
• Resources: Do you have what it takes to solve the problem from a people and material standpoint and/or are you confident you can find the resources needed in good time before you flame out.
If yes to all, proceed with GRIT, he says. Best of luck as you build.
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.