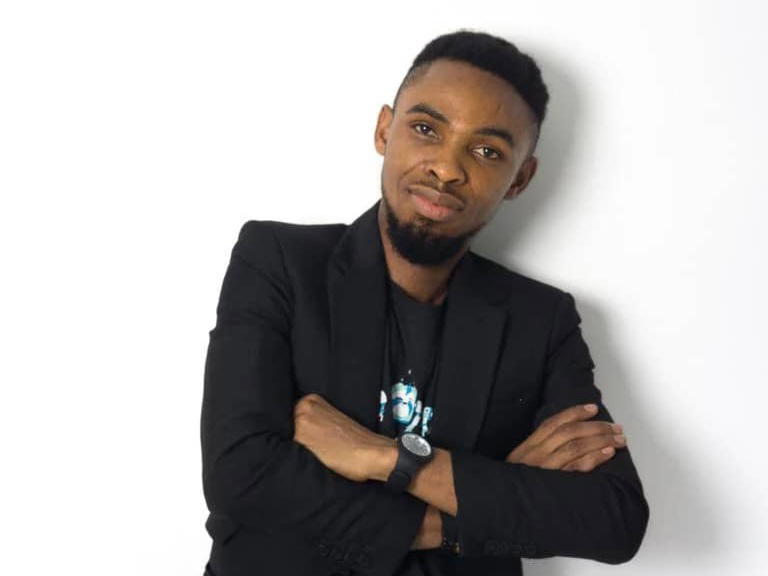
By Adetutu Audu
Tolu Adetuyi is a Nigerian technologist and Senior Product Manager with over a decade of experience driving innovation at the intersection of software development and financial technology. He holds a degree in Computer Science from Adekunle Ajasin University.
Adetuyi’s career spans some of Africa’s most impactful fintech ventures. He played a pivotal role in scaling Moniepoint’s infrastructure to serve over 16 million users and led product innovation at Accounteer during its acquisition run-up. Today, he serves as Co-founder and Chief Innovation Officer at Prembly, a Y Combinator–backed identity infrastructure company operating across Africa and the U.S., where he focuses on building secure, scalable digital identity systems.
In this interview, Adetuyi reflects on his career journey, shares lessons from the frontlines of product leadership, and offers his perspective on the future of fintech, digital identity, and innovation in Nigeria and beyond.
You led product growth of a notable Fintech company, overseeing growth initiatives for a $1B+ fintech unicorn. Tell us a bit about the journey.
Being part of Moniepoint’s early growth story was one of the most defining experiences of my career. At that stage, we were focused on building foundational systems that could scale sustainably across Nigeria’s complex financial terrain. I led key product growth initiatives that helped equip over 150,000 agents, reaching more than 16 million people with access to essential financial services.
It was more than just growth; we were building infrastructure where none existed, making financial access as local and human as possible. Everything was rooted in deep market immersion, from streamlining POS terminal distribution to designing agent tools that worked across the 36 states in Nigeria. What excites me most in hindsight is seeing those early systems still powering the scale Moniepoint has achieved today. It’s a reminder that early product-market fit decisions, when done right, can ripple far beyond their moment.
What are the essentials of AI models in KYC executions?
AI in KYC (Know Your Customer) has moved far beyond document scanning. At its core, effective AI-driven KYC relies on four essentials: identity data diversity, risk-weighted decisioning, explainability, and compliance alignment. You need high-quality datasets that go beyond just government-issued IDs, including biometric, behavioral, and transactional data. The model must be risk-aware, able to tier customers dynamically based on contextual risk factors. Explainability is crucial; if a KYC model flags a customer, we must be able to explain why, especially under regulatory scrutiny. Lastly, it must evolve with compliance requirements, both local and global. At Prembly, we’re building models that bring together these elements to enable fast, secure, and inclusive onboarding, even for those outside the traditional banking net.
What is the role of AI models in combating or reducing financial fraud and identity theft?
AI is our strongest ally in the war against fraud. Traditional systems react to fraud after it happens. AI models, on the other hand, can predict and prevent it. At Prembly, we build behavioral fraud models that don’t just look at what users say, but what they do. When someone tries to impersonate a legitimate user, patterns emerge in timing, typing, geolocation, device usage, and transaction flows. AI picks up on these subtle anomalies, even when humans cannot. More importantly, AI allows for real-time decision-making, blocking suspicious transactions in milliseconds. But beyond detection, it also aids investigation by clustering similar fraud attempts and identifying attack patterns that evolve.
You are presently the Chief Innovation Officer. What does being a Chief Innovation Officer mean?
Being Chief Innovation Officer is not just about chasing the next shiny object. It’s about building systems that foster repeatable innovation. I see myself as a bridge between what’s possible and what’s necessary, aligning emerging technologies with real-world business outcomes. My work spans product strategy, AI experimentation, partnership development, and market intelligence. I spend time deeply with engineers and customers alike, asking the right questions, spotting trends before they go mainstream, and ensuring that we stay ahead of the curve while staying grounded in our mission. True innovation isn’t about launching features; it’s about solving the right problems, sustainably, scalably, and ethically.
Which sectors do we need to apply more innovation in Nigeria?
Nigeria is ripe for innovation in several sectors, but I’d highlight three: identity infrastructure, education, and agriculture. Our fragmented identity systems hinder access to finance, healthcare, and voting, we need interoperable digital identity platforms with local context and strong privacy. In education, the biggest opportunity is in foundational literacy and job-readiness. With AI and mobile learning, we can personalize learning at scale. And in agriculture, innovation must focus on traceability, weather intelligence, and farmer credit scoring, unlocking capital and reducing post-harvest losses. The opportunity isn’t just in technology, but in localized delivery models that reflect the Nigerian reality.
What is the way forward for the Fintech sector in Nigeria?
The next chapter for Nigerian fintech is infrastructure and interoperability. We’ve built great user-facing apps; now it’s time to fix what’s under the hood. Open APIs, consent-driven data sharing, and embedded finance rails will enable a new wave of B2B and developer-focused fintechs. Financial inclusion must go beyond onboarding; it must include credit, insurance, and wealth. The winners will be those who collaborate, not those who compete in silos. We also need a greater push for financial literacy. As access increases, so must consumer understanding. Finally, we must invest in talent, not just engineers, but product thinkers and compliance leaders who can build globally relevant solutions across Africa and beyond.
How do you perceive the role of regulation in the Fintech space in Nigeria?
Regulation is not a roadblock; it’s a runway. But the key is agility. Our regulators need to move from enforcement-first to innovation-partnership models. We need regulatory sandboxes, clearer licensing pathways, and adaptive compliance frameworks that grow with the ecosystem. At the same time, fintechs must engage proactively, not just when there’s a crisis. The recent waves of clampdowns show that trust is currency. The fintechs that will endure are those that see regulation as part of product design, not an afterthought. We must build a system where innovation and trust grow side by side, because at the end of the day, finance runs on trust.
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.