By Kenneth Oboh
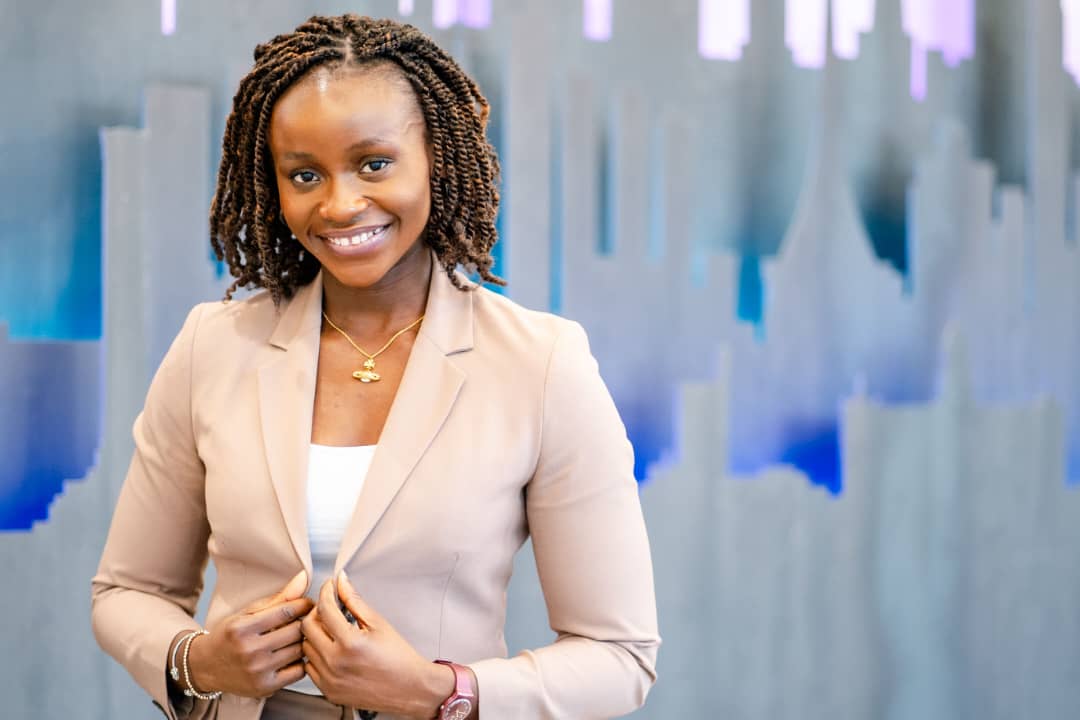
In an age where digital finance is transforming economies and breaking traditional barriers, the conversation around regulation and inclusion has never been more urgent. We sat down with Yetunde Amodu, a respected legal expert in corporate and financial services law, to discuss how fintech regulation can foster—not hinder—financial inclusion across emerging economies.
The fintech industry is growing rapidly, especially in Africa. What do you see as the biggest regulatory challenge right now?
Yetunde Amodu: The biggest challenge is achieving the right balance between innovation and regulation. Many regulators still operate within frameworks designed for traditional financial institutions, which often leaves fintech companies navigating grey areas. This regulatory uncertainty can stifle innovation and discourage smaller players from entering the market—yet these are the very actors that often drive inclusion by serving the unbanked and underbanked populations.
How can regulators create an enabling environment for both innovation and inclusion?
Yetunde Amodu: It starts with adopting a principles-based approach rather than a rigid rules-based framework. Regulatory sandboxes, for example, are excellent tools that allow fintechs to test products under the regulator’s supervision. There’s also a need for more public-private collaboration. When policymakers work hand-in-hand with innovators, they develop smarter, more adaptive regulation that considers both risk and opportunity.
What role does legal expertise play in building an inclusive financial system?
Yetunde Amodu: Legal experts act as the bridge between innovation and compliance. My work involves interpreting complex regulations and helping fintech companies navigate them without losing sight of their mission to democratize access to finance. We also advocate for legal reform where outdated policies are holding progress back. Ultimately, sound legal guidance can help fintechs scale sustainably while protecting consumers and supporting national financial inclusion goals.
What’s one area of fintech that you believe has the most potential to drive financial inclusion?
Yetunde Amodu: Mobile lending platforms and micro-savings tools. These platforms allow people with no formal banking history to access credit and grow savings securely, often using just a phone. But they need to be regulated in ways that encourage ethical lending practices, protect users from exploitation, and promote transparency. That’s where smart regulation really matters.
And what advice do you have for fintech startups navigating the legal landscape in Nigeria and similar economies?
Yetunde Amodu: Don’t treat compliance as an afterthought. Engage with legal professionals early, understand your obligations, and maintain good corporate governance from the start. Compliance can be a strategic advantage, especially when scaling or seeking investment. Also, keep the dialogue open with regulators; proactive communication goes a long way in building trust.
Final thoughts?
Yetunde Amodu: A financially inclusive economy is possible—but it demands intentionality. Regulators must evolve, fintechs must act responsibly, and legal professionals must continue to advocate for forward-looking policies. If we get this right, we won’t just grow the fintech sector—we’ll transform lives.
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.