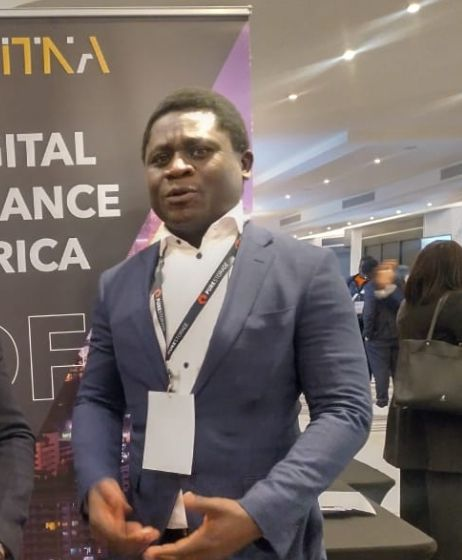
By Nwafor Sunday
In a recent conversation with the media, Adeyemi, a recognized expert in telecommunications and fintech, shared his perspectives on the transformative role digital payment solutions play in advancing financial inclusion. Drawing on over 15 years of experience in digital financial services, business development, and strategic leadership, Adeyemi discussed how digital payment technologies have the power to change lives, particularly for the unbanked and underserved populations.
“Digital payment solutions have redefined what financial inclusion means,” Adeyemi explained. “In regions with limited access to traditional banking, these technologies offer people a bridge to the formal financial system, providing services right at their fingertips.” According to Adeyemi, the true strength of digital payments lies in their accessibility, especially through mobile phones. “For many people in underserved areas, all they need is a mobile phone to gain access to services like money transfers, bill payments, and purchases. This mobile-first approach is making financial services available to communities that were previously out of reach.”
Adeyemi highlighted the impact of digital payments on microfinance, which is a key area where these solutions create tangible benefits. “One of the most exciting things about digital payments is how they open up access to microloans and small-scale finance. By analyzing alternative data, like mobile usage and transaction patterns, fintech companies can assess creditworthiness in a way that wasn’t possible before. This makes it easier for small business owners or farmers to access the funds they need to grow,” he noted. For Adeyemi, the ability to repay these loans in manageable amounts through mobile wallets further supports financial stability, reducing the risk of default.
He also emphasized how digital payments foster savings habits among users. “Many digital wallets now come with savings options, allowing people to put aside small amounts regularly. This helps build financial discipline, and for many individuals, it’s the first step toward financial security,” he observed. With these features, digital payments are not only facilitating daily transactions but are also enabling users to plan for future investments in areas like education and healthcare, which can significantly improve quality of life.
The conversation turned to the role of digital payments in international remittances, which Adeyemi believes is one of the most impactful aspects of financial inclusion. “For families relying on remittances, digital payments have been a game-changer,” he explained. Traditional methods for cross-border transfers often involve high fees and long processing times, making it difficult for recipients to access funds promptly. “With digital solutions, people can receive funds instantly and affordably, which is particularly critical for families in rural areas where physical banking facilities are few and far between.”
Beyond individual financial access, Adeyemi also spoke about the economic uplift digital payments bring to communities. “As more people use digital payment solutions, informal transactions become part of the formal economy. This shift provides a wealth of data that can inform financial programs tailored to community needs,” he said. “Businesses also benefit, as they can use transaction data to better understand their customers and offer relevant products and services. It’s a win-win situation for everyone.”
However, Adeyemi acknowledged that adopting digital payment solutions comes with its share of challenges. “Building trust is paramount. Many users are concerned about the security of their transactions and the risk of fraud. To address this, fintech companies need to invest in robust cybersecurity and educate users on safe practices,” he advised. Regulatory compliance is another area he sees as essential for the industry’s growth. “Technology often moves faster than regulation, so it’s crucial to have open communication between fintech firms and regulators. Together, they can create a framework that encourages innovation while safeguarding consumers.”
Looking ahead, Adeyemi expressed optimism about the future of digital payments and their potential to deepen financial inclusion. “We’re just scratching the surface of what digital payments can do. With technologies like blockchain and AI, we can take financial inclusion to the next level,” he said. Blockchain, for instance, promises greater transparency and security, particularly in cross-border payments. AI, meanwhile, can drive advanced analytics, helping providers assess credit risks and prevent fraud more effectively.
In Adeyemi’s view, digital payment solutions are not just financial tools—they are catalysts for social and economic transformation. “These solutions enable economic participation for millions who were previously excluded from the financial system. They create opportunities, build trust, and empower people to take control of their finances,” he concluded. For Adeyemi and other advocates of financial inclusion, the future of digital payments holds immense promise for creating a more equitable and financially inclusive world.
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.