By Juliet Umeh
Financial technology, Fintech platforms are playing a transformative role in bridging the financing gap for small and medium-sized enterprises, SMEs, in Nigeria, says financial expert Oluwatosin Alabi.
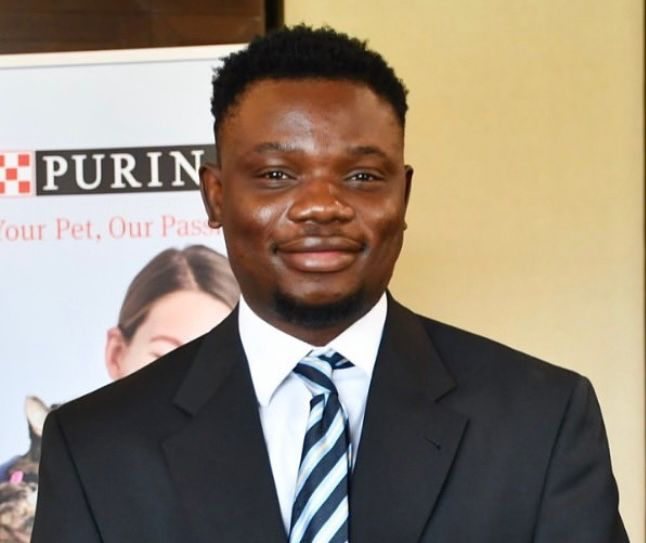
Alabi, an MBA candidate specializing in Finance and entrepreneurship at the University of Arkansas, explained that SMEs, despite contributing significantly to Nigeria’s economy, remain severely underfunded.
Alabi said: “Small and medium-sized enterprises account for 96% of businesses in Nigeria and contribute over 48% to the country’s GDP, according to the Nigerian Bureau of Statistics. Yet, these businesses face a persistent and crippling financing gap.”
Citing a report by the International Finance Corporation, IFC, he noted that Africa’s total SME finance gap is estimated at $331 billion, presenting a major barrier to growth, innovation, and employment across the continent.
Traditional lending models have long excluded SMEs due to high collateral demands, limited credit histories, and bureaucratic bottlenecks. However, fintech is disrupting this status quo by leveraging technology and alternative data to improve financial inclusion.
“Nigeria’s fintech sector leads Africa, accounting for over 60% of all venture funding into startups on the continent in 2022,” Alabi said, citing the Partech Africa Report.
Digital lenders and neobanks such as FairMoney, Carbon, Renmoney, and KiaKia are using mobile data, spending behavior, and transaction history to assess creditworthiness and disburse loans without the need for traditional banking infrastructure.
According to Statista, Nigeria’s alternative lending market is worth over $231 million as of 2024 and is projected to grow by nearly 24 percent annually through 2028, highlighting fintech’s growing influence on the nation’s financial ecosystem.
A striking example of fintech’s impact is PalmPay, which has expanded rapidly to serve over 35 million users and more than 1 million SMEs. The platform integrates financial tools with mobile services, enabling small business owners to transact, save, and access credit with unprecedented ease.
Public institutions are also playing a complementary role. The Development Bank of Nigeria, DBN, supported by multilateral agencies, has disbursed more than N1 trillion to SMEs since inception. Meanwhile, fintech firms are acting as agile last-mile distributors of financial products to Nigeria’s vast informal sector.
Alabi added: “This hybrid finance ecosystem, powered by institutional support and fintech innovation, can scale to reach millions of underbanked entrepreneurs across the country.”
To fully bridge Nigeria’s SME financing gap, Alabi recommends the following:
Expand Alternative Credit Infrastructure: Broaden the use of telecom, utility, and behavioral data to evaluate borrowers more inclusively.
Foster Bank-Fintech Partnerships: Create regulatory frameworks that enable banks to supply capital while fintechs manage distribution and risk.
Promote Financial Literacy and Data Ethics: Ensure borrowers are well-informed and that data-driven lending respects privacy and ethical standards.
Encourage Regulatory Innovation: The Central Bank of Nigeria, CBN, and other regulators must create an enabling environment while safeguarding consumers.
Scale Development Finance Initiatives: Expand DBN’s reach by working with private lenders and state-level credit programs.
Alabi noted that the future of inclusive growth in Nigeria depends on empowering SMEs through innovative financial solutions.
He said: “By combining fintech disruption with smart regulation and institutional backing, Nigeria can close its SME financing gap and unlock the full potential of its entrepreneurial ecosystem. “Financial inclusion is not just a social cause, it’s an economic necessity.”
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.