
Mr. Godson Ukpevo, the CEO of Veritas Glansvill Pension
pension
By Luminous Jannamike
Mr. Godson Ukpevo, the CEO of Veritas Glansvill Pension, says greater deployment of automation technology in Nigeria’s pension system has eliminated quackery and other database problems that hitherto plagued the industry.
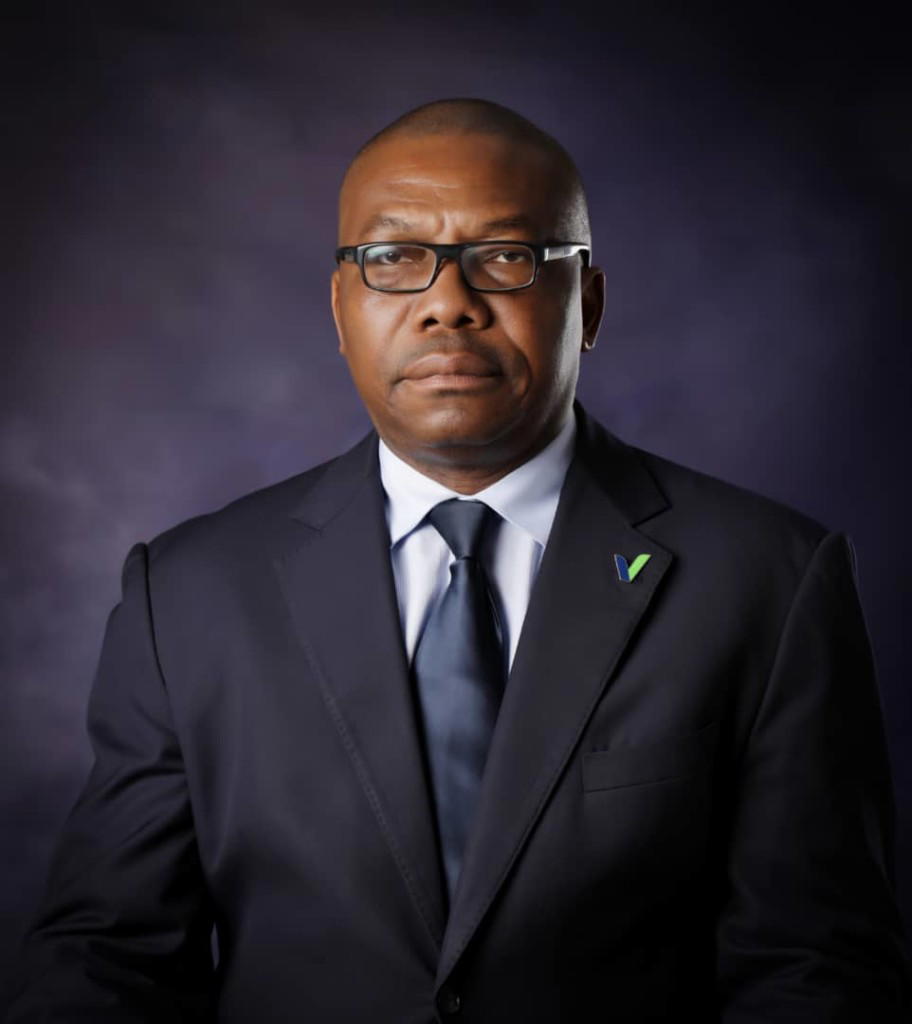
Mr. Godson Ukpevo, the CEO of Veritas Glansvill Pension
According to him, the enhanced contribution registration system, which made the National Identity Card number a compulsory field for every contributor, and the use of Personal Identification Number, which can only be generated by a licensed Pension Fund Administrator (PFA), as means of access to contributions has made the industry immune to fraudulent practices.
Windows for porting of PFAs underway as PenCom deploys ECRS(Opens in a new browser tab)
In this interview with our correspondent, Ukpevo also highlights the value of pension plans for young people, especially those in the informal sector, as well as explains why Veritas Glansvill embarked on sensitisation of NURTW members on the recently launched micro-pension scheme by President Muhammadu Buhari.
EXCERPTS:
Many Nigerians think pension is for old people and those in retirement. How does it concern the youths?
What many youths fail to realise in Nigeria is that eventually theh will get old and that the best time to start thinking about that eventuality is now and not by the time when perhaps it may be too late. While retirement happens in old age, planning for it must begin in the youthful days, right from the very first day a young person starts work or business. This is why PENCOM has designed the contributory pension scheme and micro-pension plan for all Nigeria irrespective of age.
How does pension work for those in the informal sector?
Everyone who works needs to remember that they will not work forever. At some point, we will all have to stop work, either because we retire when we reach the retirement age, or on health grounds. Having said that, a micro pension plan with a licensed PFA ensures that those in the informal sector can save something today, no matter how small, and it can be managed and invested to grow and create a nest egg for their future.
There are many informal sector unions in the country… Why has Veritas Glansvill singled out NURTW members for sensitization on micro pension plan?
The NURTW is one of the strongest unions in the informal sector and they occupy a very strategic position in national economy because of their number of members. They are represented in every state, local government and major city in the country. For a micro-pension scheme like this, if you’re able to bring them on board, becomes an incentive and motivation to other similar unions and people in the informal sector.
You know pension has never been in the informal sector. If you don’t get the buy-in of people that it is meant for, it will be a failure. So, you have to go after the critical unions in that sector to talk to them to key into the scheme so that they can benefit their members.
Do you have a package that is tailored towards their specific needs?
The pension industry is highly regulated by the National Pension Commission. So, everything you do about pension administration is by the rule that has been set down. You can’t deviate from those rules in terms of even investment. You know the fund administrators don’t even keep the pension money they collect. The money is kept with the pension fund custodians.
So, the special package we have for the unions is within the guidelines and regulations of PENCOM. Some of the things we have for them is introducing our insurance related added services and health insurance for their members at very subsidised rates.
We are not just collecting their monies but also investing the money and ensuring that the returns on investment is very good. You know PFA’s can collect these monies and not invest them properly and at the end the expected percentage growth will be achieved. So, one of the things we are bringing on board is a very strong investment plan for the contributors.
How would you address database related problems in the pension industry?
PENCOM has realised the importance of strong information Technology and database. You may have heard that the pension regulator is now migrating from the old contribution registration system to what is called the enhanced contribution registration system which is highly automated and foolproof. There is also a critical feature of this new system which is the use of the National Identity Card number. It is now a compulsory field for every contributor.
You know two persons can never have the same number and one person cannot have two different numbers. So with such a unique identifier keyed into the secured system database, no contributor can have multiple accounts because we have captured him with his National ID card number. So, the system now is foolproof. It’s been tightened further to ensure that those database problems we used to have no longer occur.
How about professional misconducts and quackery in the pensions industry?
You can’t really have quackery in the industry because all the PFAs are licensed. Everybody working in those PFAs must be engaged formally.
There are no quacks in the industry and I boldly say so. You can’t claim to be an agent who is marketing pension accounts without working as a staff of a licensed PFA because when you open a pension account for a contributor, there is a Personal Identification Number that is generated automatically.
A quack cannot give you that PIN. It is difficult for a quack to operate in this industry. Also, a lot of technology is been introduced to support the pensions system. Contributions can now be made through online means, access to them is processed through the internet and PFAs are reaching out more to the clients.
Another good thing is PFAs can no longer collect monies in cash like banks, because the pension fund custodians are a different management entirely. To clarify, if I register you as a contributor under Veritas, I cannot collect one Kobo from you.
The money is paid directly into the account of the custodians. If you want to collect your benefits, I cannot pay you but will only process your application to the custodian who now pays you. So, there are a lot of controls within the system.
That’s why you have not really heard of the kind of fraud that use to happen in the old pensions system in this new automated system. These are some of the things PENCOM has tightened.
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.