By Josephine Agbonkhese
Buried in the middle of the National Credit Guarantee Company’s first-year impact card, set in smaller type than the billions above it, sits a percentage: 33.5%. It is labelled first-time borrowers, and beneath it the card calls it a major financial inclusion milestone.
Applied to the 67,512 end-borrowers reached in year one, 33.5 percent represents approximately 22,600 Nigerians who entered the formal credit system for the first time in their lives.
Nigeria’s credit exclusion problem is usually described as a collateral problem, an estimated 80 percent of MSMEs being locked out because they cannot pledge assets and lenders will not take the risk. But collateral is only the first gate; the second is history. A bank that cannot see what a borrower did with their last loan has no basis to price their next one, so it either declines or prices as though they are the riskiest borrower in the country.
This creates a systemic trap: a business owner cannot get a loan without a credit history, and they cannot build a credit history without a loan.
A guarantee breaks that loop exactly once. NCGC absorbs up to 60 percent of the lender’s risk on that first facility, providing enough risk cover for the credit committee to say yes to someone it would otherwise never have underwritten. Once the borrower repays, a twelve-month record of performance sits in a bank’s system and in the credit bureaux.
The second loan does not need a guarantee. The ₦46.95 billion mobilized was the mechanism, but those 22,600 permanent credit files are the actual long-term asset.
A first loan is only an asset if it is repaid. If the guarantee caused a bank to lend to someone
who cannot service the facility, NCGC has built a default record rather than a credit history.
That is the specific danger of guarantee schemes and the reason NCGC’s cover is partial rather than total. The lender retains 40 percent of the exposure precisely so that it continues to underwrite properly. NCGC’s terms reinforce this: cover pays out only after the lender has exhausted its recovery processes and met its compliance obligations. Sloppy lending does not
get rescued.
Loan books do not fully reveal themselves in twelve months. The cohort of first-time borrowers written in late 2025 and early 2026 will mature through 2027, and the non-performing loan rate on that cohort will dictate whether this initiative expanded the bankable population or simply
confirmed lenders’ initial risk aversion.The impact report records 11,374 female-owned end-borrowers, representing 16.8 percent of
the total.
Recognizing this gap in a market where women face steeper barriers to formal credit
despite strong repayment records, the company built a dedicated response around it.
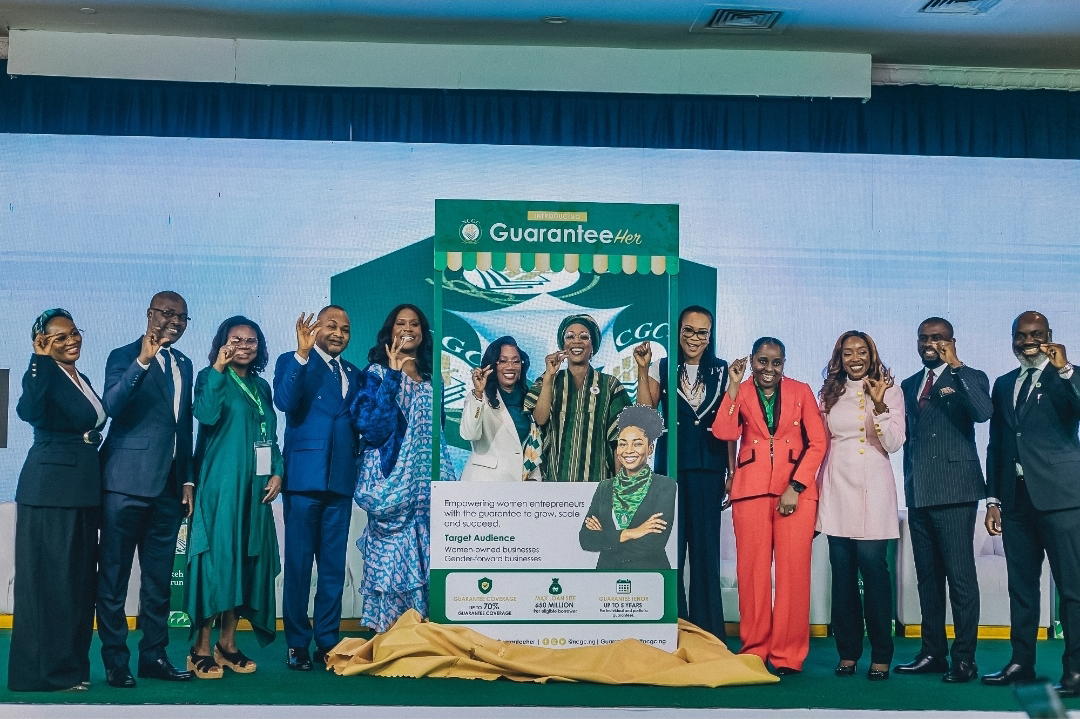
GuaranteeHer, formally backed by the Federal Government with key support from Minister of
Finance Taiwo Oyedele and Minister of Women Affairs Imaan Sulaiman-Ibrahim, is a
gender-responsive guarantee scheme targeting over ₦100 billion in financing for women-owned and women-led MSMEs over five years, aiming to reach over 20,000 businesses and support upwards of 150,000 jobs. Its strategic targets address inadequate collateral, informal business documentation, and perceived lending risk.
Complementing this is GLOW (Guaranteed Loans for Women), run in partnership with the Bank of Industry (BOI), which adds ₦10 billion with NCGC providing 25 percent cover on BOI lending to women-led enterprises across manufacturing, processing, ICT, healthcare, and renewable energy.
NCGC currently operates across 25 states plus the FCT.
While representing a broad footprint,
eleven states remain unreached, and a geographic count does not detail depth of concentration across economic hubs like Lagos, Ogun, Rivers, and Abuja.
The distribution architecture relies on 19 institutions: 13 commercial banks, 3 microfinance banks, and 3 development finance institutions.
While commercial banks hold the capital
capacity, microfinance banks hold the last-mile reach into the micro-enterprises that face the greatest hurdles accessing credit. Expanding beyond three microfinance banks will be essential to reaching lower-tier market segments effectively.
Going forward, the institution will be measured on concrete outcomes:
First-Time Borrower Performance: Repayment rates on the initial 22,600 borrower cohort.
Gender Ratio Movement: Growth in female representation past the 16.8 percent baseline via GuaranteeHer and GLOW.
Distribution Channel Expansion: Deeper integration with microfinance networks to reach micro-enterprises.
Graduation to Standalone Credit: The transition of guaranteed borrowers into independent, unguaranteed commercial bank clients.
The true success of the guarantee model lies not just in expanding its active portfolio, but in
creating borrowers who eventually no longer require a guarantee to access credit.
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.