By Emmanuel Okogba
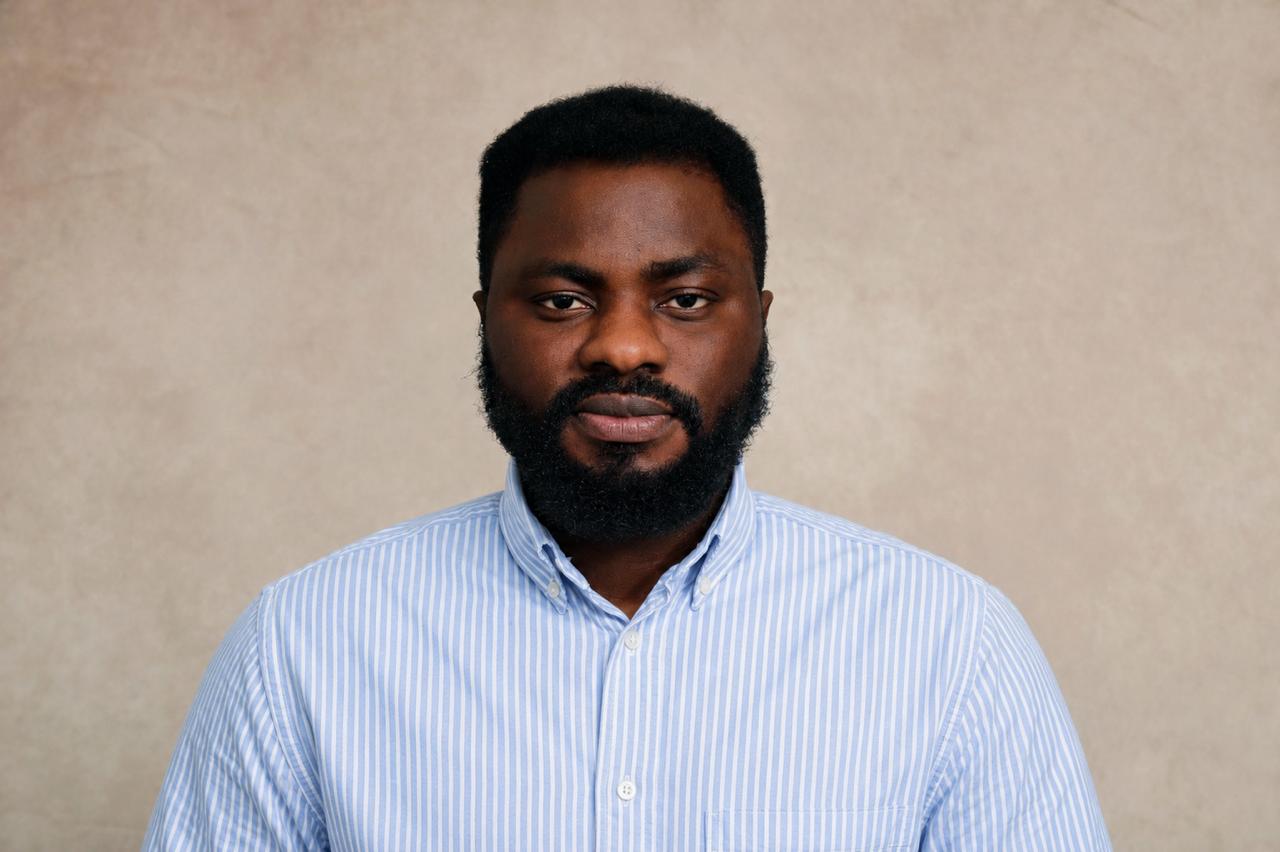
As Africa’s cross-border payments market continues its rapid expansion, a senior payments infrastructure engineer, Henry Ivwighre, has identified weak payment rails, fragmented banking systems and poor infrastructure design as major factors slowing seamless financial transactions across the continent.
While speaking in a paper titled “Why Cross-Border Payment Rails Break at Scale, and What Engineers Are Doing About It,” Ivwighre noted that despite Africa’s growing digital economy, moving money between African countries remains slower and more expensive than sending funds to Europe.
He observed that intra-African trade accounts for only about 15 per cent of the continent’s total trade, compared with 58 per cent in Asia and 67 per cent in Europe, attributing part of the disparity to inefficient payment infrastructure.
According to him, international transfers within Africa still cost eight per cent or more and can take several days to clear, while an estimated 88 per cent of intra-African transactions are routed through foreign intermediary banks before reaching their final destinations.
The engineer noted that the continent’s cross-border payments sector, valued at about $329 billion in 2025, is projected to grow to approximately $1 trillion by 2035, making the need for resilient and scalable payment infrastructure increasingly urgent.
Ivwighre, who works as a senior engineer at a global payments infrastructure platform that processed more than $1 billion in international payments in 2025, said much of the industry’s challenge lies not in developing new products but in ensuring that payment systems remain reliable as transaction volumes increase.
“The instinct when you’re scaling fast is to patch things and move on. But a shortcut you take this quarter turns into an incident two quarters later, once volume has tripled and nobody remembers why the workaround was there in the first place,” he said.
He explained that much of his work focuses on service boundaries and modular system design, describing them as critical engineering decisions that determine whether payment platforms can expand into new markets or adapt to changing regulatory requirements without undergoing complete system overhauls.
According to him, payment platforms serving Africa and Latin America face unique engineering challenges because they must simultaneously contend with volatile currencies, fragmented banking infrastructure and evolving regulatory frameworks.
“Resilience gets treated like something you add once you’re big enough to afford it. For platforms serving African and Latin American markets, that’s the wrong order.
You need it earlier, precisely because the rails underneath you are less forgiving,” Ivwighre stated.
He further pointed out that Africa already accounts for about two-thirds of global mobile money transaction volume, while Nigeria’s NIBSS Instant Payments platform processes more real-time domestic transactions than many payment systems in wealthier economies.
The engineer also highlighted the role of the Pan-African Payment and Settlement System, which has connected more than 150 commercial banks across 19 countries since its launch in 2022 to enable cross-border settlements in local currencies rather than through the US dollar.
While domestic payment systems across many African countries have made significant progress, Ivwighre maintained that the biggest challenge remains building reliable infrastructure that allows money to move between African markets as efficiently as it already does within individual countries.
He stressed that as payment volumes continue to grow across the continent, strengthening the engineering foundations of cross-border payment systems will be essential to supporting Africa’s expanding digital economy.
Disclaimer
Comments expressed here do not reflect the opinions of Vanguard newspapers or any employee thereof.